China’s Humanoid Robot Price War: Supply Is Surging, but Where Are the Customers?
China’s humanoid robot industry is hurtling toward a price war, with average Unitree prices dropping 72% from $85,000 in 2023 to $25,000 in 2025, even as annual sales remain below 20,000 units—a supply glut that mirro... Wuhan based GigaAI just deployed 100 SeeLight S1 robots into real homes for free in Q3 2026, und...
Published byEdited with DeepSeek-V4-ProImages generated with GPT Image 1.5
China’s humanoid robot industry is hurtling toward a price war, with average Unitree prices dropping 72% from $85,000 in 2023 to $25,000 in 2025, even as annual sales remain below 20,000 units—a supply glut that mirro...
Wuhan based GigaAI just deployed 100 SeeLight S1 robots into real homes for free in Q3 2026, underscoring the industry’s fundamental problem: manufacturers can build cheap robots but still don’t know if people will pa...
Chinese firms shipped roughly 80–90% of the 13,000–18,000 humanoid robots sold globally in 2025, led by AgiBot (5,168 units) and Unitree (4,200–5,500 units), while US rivals Tesla and Figure AI shipped only about 150...
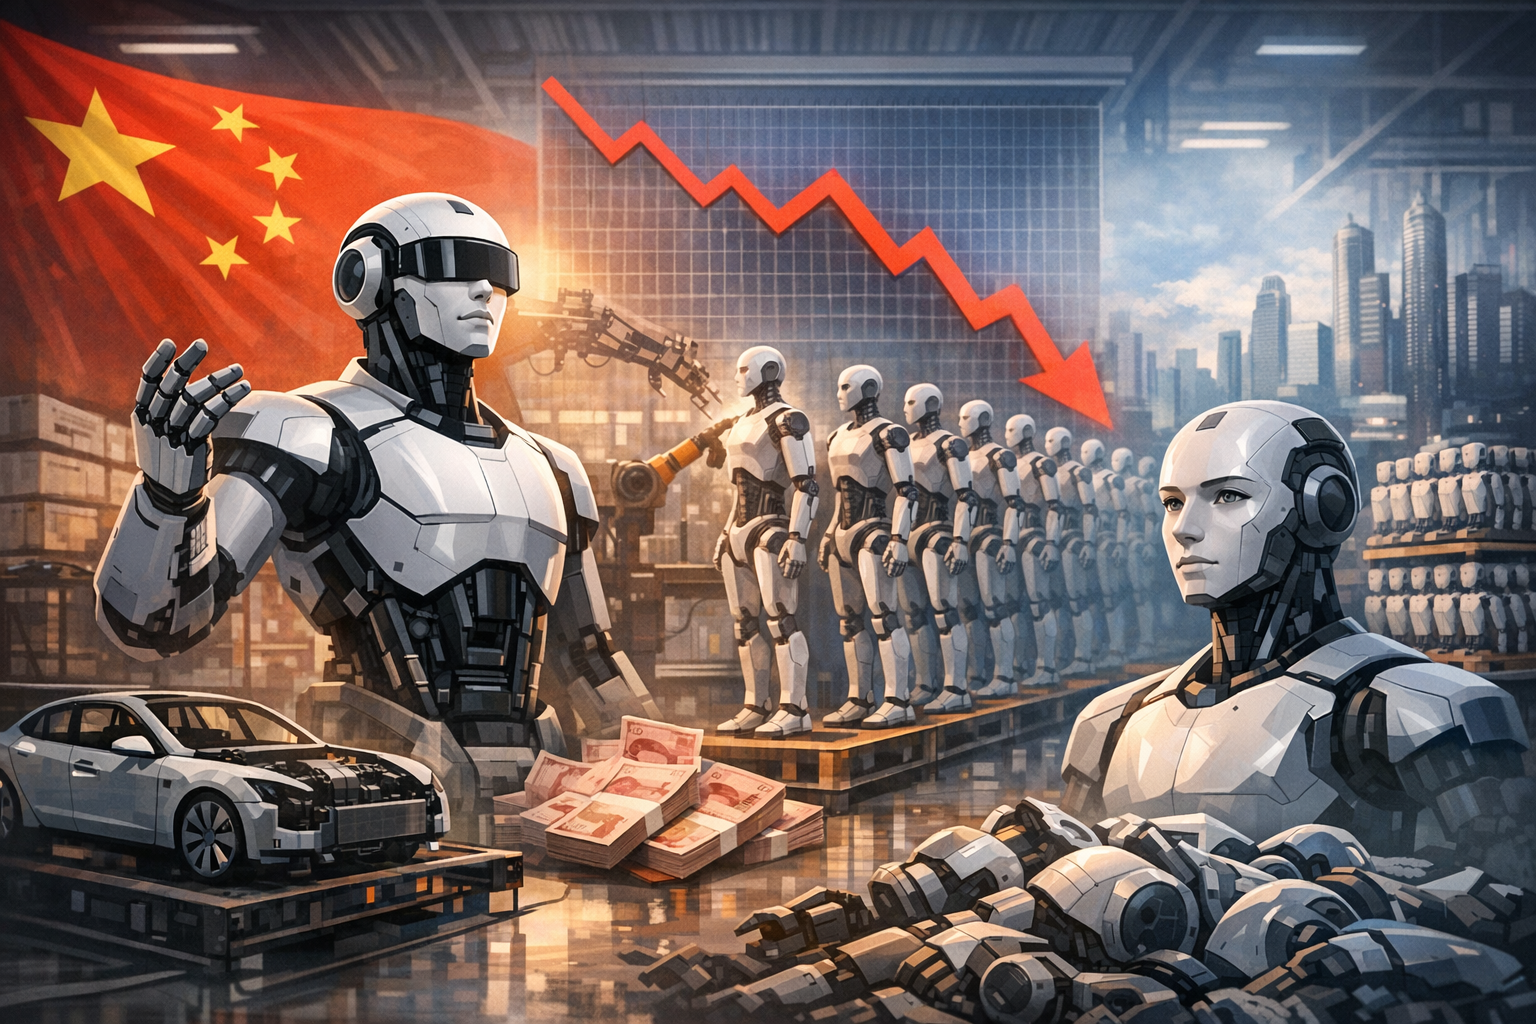
What is driving the price war fears in China's humanoid robot industry, how does it compare to the earlier EV sector collapse, and what specGigaAI’s SeeLight S1 is one of the first humanoid robots being tested in real homes, as China’s industry races to find buyers for its surging output.
AI Prompt
Create a landscape editorial hero image for this Studio Global article: What is driving the price war fears in China's humanoid robot industry, how does it compare to the earlier EV sector collapse, and what spec. Article summary: China's humanoid robot industry is experiencing severe price war fears driven by a flood of new entrants, a state mandate for rapid deployment, and a dramatic gap between surging manufacturing capacity and unproven comme. Topic tags: general, news, general web, user generated. Reference image context from search candidates: Reference image 1: visual subject "Hardware, data, and foundation models — how China's supply chain density, state-backed industrial policy, and EV-adjacent manufacturing base have made it the world's humanoid produ" source context "China Robotics Market 2026: Humanoids, Manufacturing & Global Leadership | SVRC" Reference image 2: visual sub
openai.com
China’s humanoid robot industry is moving faster than almost anyone predicted, but not necessarily in a healthy direction. In 2025, Chinese companies shipped roughly 80% to 90% of all humanoid robots globally, a dominance built on aggressive government targets, massive capital inflows, and a manufacturing ecosystem that can slash production costs faster than any other country . Yet even as prices plummet—Unitree’s average robot cost fell 72% in two years, from around $85,000 in 2023 to just $25,000 by 2025—the industry is confronting a much harder question: who actually wants to buy one ?
Studio Global AI
Continue your research
This page includes a source-backed answer you can continue inside Studio Global.
What is the short answer to "China’s Humanoid Robot Price War: Supply Is Surging, but Where Are the Customers?"?
China’s humanoid robot industry is hurtling toward a price war, with average Unitree prices dropping 72% from $85,000 in 2023 to $25,000 in 2025, even as annual sales remain below 20,000 units—a supply glut that mirro...
What are the key points to validate first?
China’s humanoid robot industry is hurtling toward a price war, with average Unitree prices dropping 72% from $85,000 in 2023 to $25,000 in 2025, even as annual sales remain below 20,000 units—a supply glut that mirro... Wuhan based GigaAI just deployed 100 SeeLight S1 robots into real homes for free in Q3 2026, underscoring the industry’s fundamental problem: manufacturers can build cheap robots but still don’t know if people will pa...
What should I do next in practice?
Chinese firms shipped roughly 80–90% of the 13,000–18,000 humanoid robots sold globally in 2025, led by AgiBot (5,168 units) and Unitree (4,200–5,500 units), while US rivals Tesla and Figure AI shipped only about 150...
China’s Humanoid Robot Price War: Supply Is Surging, but Where Are the Customers?
China’s humanoid robot industry is hurtling toward a price war, with average Unitree prices dropping 72% from $85,000 in 2023 to $25,000 in 2025, even as annual sales remain below 20,000 units—a supply glut that mirro... Wuhan based GigaAI just deployed 100 SeeLight S1 robots into real homes for free in Q3 2026, und...
Published byEdited with DeepSeek-V4-ProImages generated with GPT Image 1.5
China’s humanoid robot industry is hurtling toward a price war, with average Unitree prices dropping 72% from $85,000 in 2023 to $25,000 in 2025, even as annual sales remain below 20,000 units—a supply glut that mirro...
Wuhan based GigaAI just deployed 100 SeeLight S1 robots into real homes for free in Q3 2026, underscoring the industry’s fundamental problem: manufacturers can build cheap robots but still don’t know if people will pa...
Chinese firms shipped roughly 80–90% of the 13,000–18,000 humanoid robots sold globally in 2025, led by AgiBot (5,168 units) and Unitree (4,200–5,500 units), while US rivals Tesla and Figure AI shipped only about 150...
What is driving the price war fears in China's humanoid robot industry, how does it compare to the earlier EV sector collapse, and what specGigaAI’s SeeLight S1 is one of the first humanoid robots being tested in real homes, as China’s industry races to find buyers for its surging output.
AI Prompt
Create a landscape editorial hero image for this Studio Global article: What is driving the price war fears in China's humanoid robot industry, how does it compare to the earlier EV sector collapse, and what spec. Article summary: China's humanoid robot industry is experiencing severe price war fears driven by a flood of new entrants, a state mandate for rapid deployment, and a dramatic gap between surging manufacturing capacity and unproven comme. Topic tags: general, news, general web, user generated. Reference image context from search candidates: Reference image 1: visual subject "Hardware, data, and foundation models — how China's supply chain density, state-backed industrial policy, and EV-adjacent manufacturing base have made it the world's humanoid produ" source context "China Robotics Market 2026: Humanoids, Manufacturing & Global Leadership | SVRC" Reference image 2: visual sub
openai.com
China’s humanoid robot industry is moving faster than almost anyone predicted, but not necessarily in a healthy direction. In 2025, Chinese companies shipped roughly 80% to 90% of all humanoid robots globally, a dominance built on aggressive government targets, massive capital inflows, and a manufacturing ecosystem that can slash production costs faster than any other country . Yet even as prices plummet—Unitree’s average robot cost fell 72% in two years, from around $85,000 in 2023 to just $25,000 by 2025—the industry is confronting a much harder question: who actually wants to buy one ?
Studio Global AI
Continue your research
This page includes a source-backed answer you can continue inside Studio Global.
What is the short answer to "China’s Humanoid Robot Price War: Supply Is Surging, but Where Are the Customers?"?
China’s humanoid robot industry is hurtling toward a price war, with average Unitree prices dropping 72% from $85,000 in 2023 to $25,000 in 2025, even as annual sales remain below 20,000 units—a supply glut that mirro...
What are the key points to validate first?
China’s humanoid robot industry is hurtling toward a price war, with average Unitree prices dropping 72% from $85,000 in 2023 to $25,000 in 2025, even as annual sales remain below 20,000 units—a supply glut that mirro... Wuhan based GigaAI just deployed 100 SeeLight S1 robots into real homes for free in Q3 2026, underscoring the industry’s fundamental problem: manufacturers can build cheap robots but still don’t know if people will pa...
What should I do next in practice?
Chinese firms shipped roughly 80–90% of the 13,000–18,000 humanoid robots sold globally in 2025, led by AgiBot (5,168 units) and Unitree (4,200–5,500 units), while US rivals Tesla and Figure AI shipped only about 150...
That question is now visible in an unusual experiment unfolding in Wuhan. Startup GigaAI recently deployed the first batch of 100 SeeLight S1 humanoid robots into real households on a free trial basis, a bid to discover whether ordinary families will embrace a machine that can cook, do laundry, and fold clothes . The trial, set to scale up through the first half of 2027, is China’s first large-scale real-world test of a general-purpose home humanoid—and it exposes the central tension of the entire sector. Factories are poised to produce hundreds of thousands of units, but the evidence of genuine consumer demand is still largely missing .
The Overcrowding Problem: Hundreds of Companies, One Narrow Playbook
China now hosts roughly half of all humanoid robot companies worldwide, estimated at around 200 firms . The proliferation is so extreme that the National Development and Reform Commission, China’s top economic planning body, issued a rare public warning in late 2025 about bubble risk in the sector, pointing to more than 150 companies producing remarkably similar robots . Founders and investors openly use the same term that came to define China’s electric vehicle market: involution, or self-destructive competition .
That parallel is not casual. The EV sector saw hundreds of startups emerge, prices collapse, and dozens of companies fold as production far outstripped consumer demand. The humanoid sector, with annual sales still below 20,000 units in China, is already pricing like a mass market—a signal that the price war may be arriving even earlier in the product lifecycle . Analysts at Caixin, Reuters, and several research firms have explicitly drawn the comparison, warning of overcapacity and margin destruction ahead .
How the State Supercharged Supply Before Demand Existed
A government mandate to put 10,000 humanoid robots into use by 2026 has accelerated production planning regardless of actual commercial pull . Meanwhile, the sector absorbed an estimated $8.15 billion in funding in 2025, a jump of more than 170% year-on-year, with Chinese humanoid robot companies raising nearly 17 billion yuan ($2.4 billion) in the first nine months alone . The Solactive China Humanoid Robotics Index surged nearly 60% through October 2025 before investor unease set in .
By mid-2026, the constraint was no longer building robots—it was finding people to pay for them. Lingyi iTech vice president Philip Yang told CNBC that the company aims to reach 500,000 robots a year by 2030, and that production at that scale could halve the current ~$30,000 price. Morgan Stanley analyst Sheng Zhong supplied the sobering counterpoint: the bottleneck now “is no longer production capacity—it is the list of customers willing to pay” .
The Evidence in Market Data: Shipments, Share, and Prices
Shipments and market share (2025)
Global humanoid robot shipments hit roughly 13,000 to 18,000 units in 2025, a jump of approximately 508% year-on-year .
Chinese firms accounted for roughly 80–90% of all shipments .
Shanghai-based AgiBot shipped an estimated 5,168 units, giving it about 38–39% of the global market. Unitree shipped between 4,200 and 5,500 units, depending on the source. Together, the two leaders are projected to control nearly 80% of the Chinese market in 2026 .
By contrast, US companies Tesla and Figure AI each shipped only around 150 units in 2025 .
Price collapse
Unitree’s average humanoid robot price fell from ~$85,000 in 2023 to ~$25,000 by 2025, a 72% drop .
Unitree’s consumer-oriented G1 now starts at $16,000, while its new dual-arm R1 launched at just 26,900 yuan ($3,968) .
Noetix Robotics introduced the Bumi robot for 9,998 yuan (~$1,450), one of the first consumer humanoids below $1,500 .
Rental prices for Unitree’s popular G1 fell to 4,000–5,000 yuan/day in mid-2025, barely one-fourth of peak, and after Spring Festival 2026 dropped further to under 1,000 yuan/day .
The 2026 market range now spans from $5,900 for budget models to over $250,000 for enterprise-grade systems .
GigaAI’s Home Trial: A Free Test for a Product Nobody Has Proven They Want
Wuhan-based GigaAI’s SeeLight S1 trial is the most vivid illustration of the demand gap. The wheeled humanoid is designed for chores: it can cook, do laundry, clean, and fold clothes, though some tasks—like folding—still take more than 10 minutes . The first 100 units were deployed in employee housing in Wuhan’s Optics Valley in Q3 2026, with free public home trials targeting families with elderly members, children, or pets launching in the first half of 2027 . GigaAI expects to reach a retail price of about $15,000 by mid-2027, and its WeChat account received more than 2,000 messages from people eager to sign up .
The trial is a genuine milestone, but it also lays bare the underlying problem. Companies are spending enormous sums to build robots cheap enough to place in homes—and then giving them away for free just to test whether any viable consumer market exists. As CNBC put it, the question is no longer “can we build it” but “who will buy it” . Some analysts argue the robotics sector may need at least five more years to reach its equivalent “EV moment” of mass adoption. If that’s correct, the current price war is arriving dangerously early .
For now, China’s humanoid industry is a remarkable manufacturing success story and an open question about commercial viability. The robots are real, the prices are falling, and the factories are scaling—but the search for paying customers is only just beginning.
That question is now visible in an unusual experiment unfolding in Wuhan. Startup GigaAI recently deployed the first batch of 100 SeeLight S1 humanoid robots into real households on a free trial basis, a bid to discover whether ordinary families will embrace a machine that can cook, do laundry, and fold clothes . The trial, set to scale up through the first half of 2027, is China’s first large-scale real-world test of a general-purpose home humanoid—and it exposes the central tension of the entire sector. Factories are poised to produce hundreds of thousands of units, but the evidence of genuine consumer demand is still largely missing .
The Overcrowding Problem: Hundreds of Companies, One Narrow Playbook
China now hosts roughly half of all humanoid robot companies worldwide, estimated at around 200 firms . The proliferation is so extreme that the National Development and Reform Commission, China’s top economic planning body, issued a rare public warning in late 2025 about bubble risk in the sector, pointing to more than 150 companies producing remarkably similar robots . Founders and investors openly use the same term that came to define China’s electric vehicle market: involution, or self-destructive competition .
That parallel is not casual. The EV sector saw hundreds of startups emerge, prices collapse, and dozens of companies fold as production far outstripped consumer demand. The humanoid sector, with annual sales still below 20,000 units in China, is already pricing like a mass market—a signal that the price war may be arriving even earlier in the product lifecycle . Analysts at Caixin, Reuters, and several research firms have explicitly drawn the comparison, warning of overcapacity and margin destruction ahead .
How the State Supercharged Supply Before Demand Existed
A government mandate to put 10,000 humanoid robots into use by 2026 has accelerated production planning regardless of actual commercial pull . Meanwhile, the sector absorbed an estimated $8.15 billion in funding in 2025, a jump of more than 170% year-on-year, with Chinese humanoid robot companies raising nearly 17 billion yuan ($2.4 billion) in the first nine months alone . The Solactive China Humanoid Robotics Index surged nearly 60% through October 2025 before investor unease set in .
By mid-2026, the constraint was no longer building robots—it was finding people to pay for them. Lingyi iTech vice president Philip Yang told CNBC that the company aims to reach 500,000 robots a year by 2030, and that production at that scale could halve the current ~$30,000 price. Morgan Stanley analyst Sheng Zhong supplied the sobering counterpoint: the bottleneck now “is no longer production capacity—it is the list of customers willing to pay” .
The Evidence in Market Data: Shipments, Share, and Prices
Shipments and market share (2025)
Global humanoid robot shipments hit roughly 13,000 to 18,000 units in 2025, a jump of approximately 508% year-on-year .
Chinese firms accounted for roughly 80–90% of all shipments .
Shanghai-based AgiBot shipped an estimated 5,168 units, giving it about 38–39% of the global market. Unitree shipped between 4,200 and 5,500 units, depending on the source. Together, the two leaders are projected to control nearly 80% of the Chinese market in 2026 .
By contrast, US companies Tesla and Figure AI each shipped only around 150 units in 2025 .
Price collapse
Unitree’s average humanoid robot price fell from ~$85,000 in 2023 to ~$25,000 by 2025, a 72% drop .
Unitree’s consumer-oriented G1 now starts at $16,000, while its new dual-arm R1 launched at just 26,900 yuan ($3,968) .
Noetix Robotics introduced the Bumi robot for 9,998 yuan (~$1,450), one of the first consumer humanoids below $1,500 .
Rental prices for Unitree’s popular G1 fell to 4,000–5,000 yuan/day in mid-2025, barely one-fourth of peak, and after Spring Festival 2026 dropped further to under 1,000 yuan/day .
The 2026 market range now spans from $5,900 for budget models to over $250,000 for enterprise-grade systems .
GigaAI’s Home Trial: A Free Test for a Product Nobody Has Proven They Want
Wuhan-based GigaAI’s SeeLight S1 trial is the most vivid illustration of the demand gap. The wheeled humanoid is designed for chores: it can cook, do laundry, clean, and fold clothes, though some tasks—like folding—still take more than 10 minutes . The first 100 units were deployed in employee housing in Wuhan’s Optics Valley in Q3 2026, with free public home trials targeting families with elderly members, children, or pets launching in the first half of 2027 . GigaAI expects to reach a retail price of about $15,000 by mid-2027, and its WeChat account received more than 2,000 messages from people eager to sign up .
The trial is a genuine milestone, but it also lays bare the underlying problem. Companies are spending enormous sums to build robots cheap enough to place in homes—and then giving them away for free just to test whether any viable consumer market exists. As CNBC put it, the question is no longer “can we build it” but “who will buy it” . Some analysts argue the robotics sector may need at least five more years to reach its equivalent “EV moment” of mass adoption. If that’s correct, the current price war is arriving dangerously early .
For now, China’s humanoid industry is a remarkable manufacturing success story and an open question about commercial viability. The robots are real, the prices are falling, and the factories are scaling—but the search for paying customers is only just beginning.
cnbc.comCNBC's The China Connection newsletter: Wonders and woes of China's robotics industry
morningstar.comChina's next export shock walks on two legs - and costs less than a ...
takshashila.org.inUse Case Challenge Confronts China's Humanoid Robot Industry
businesswire.comGlobal Humanoid Robots Market Report 2026-2040 - Business Wire
