China’s coal cushion: why its factories weathered the energy shock better
China’s coal heavy power system did not eliminate energy risk, but it gave manufacturers a short to medium term buffer: in 2023, coal generated 5,350 TWh of electricity, or 58.2% of China’s total.[34] Compared with Europe, China’s advantage was mainly lower direct exposure to gas driven electricity price spikes; EU...
Published byEdited with GPT-5.5Images generated with GPT Image 2
China’s coal heavy power system did not eliminate energy risk, but it gave manufacturers a short to medium term buffer: in 2023, coal generated 5,350 TWh of electricity, or 58.2% of China’s total.[34]
Compared with Europe, China’s advantage was mainly lower direct exposure to gas driven electricity price spikes; EU reporting says industrial gas and electricity prices remained 2–4 times higher than in the EU’s main...
Compared with Japan and South Korea, the point is not that Chinese power was always cheaper, but that China had a domestic coal to power security cushion those economies could not easily replicate.[3][14][32]
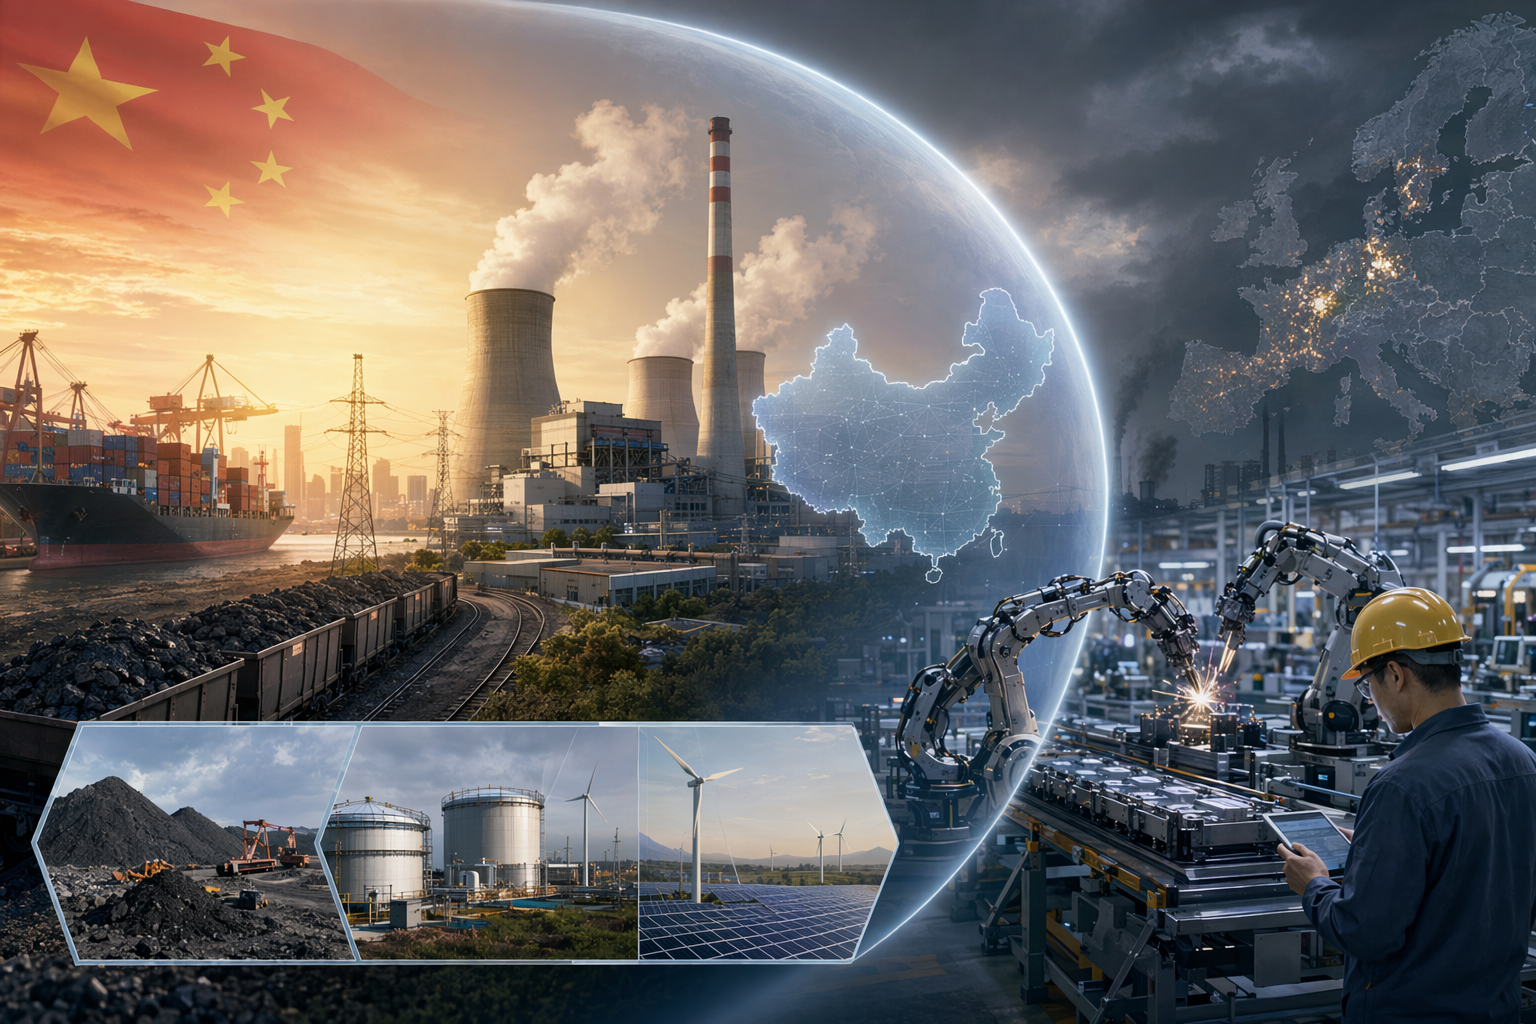
Create a landscape editorial hero image for this Studio Global article: 煤电缓冲器:中国制造为何在能源危机中更抗压. Article summary: 中国煤电结构在2021–2023年能源危机中为制造业提供了短中期缓冲:2023年煤电仍占中国发电量58.2%,叠加全球最大规模的本土煤炭生产,使企业较少直接承受欧洲式天然气—电价冲击;但煤价、限电和高碳排意味着这不是永久优势。[34][32][11]. Topic tags: china, coal, energy security, manufacturing, electricity. Reference image context from search candidates: Reference image 1: visual subject "这种结构还帮助中国在全球订单转移中保持“交付确定性”。当欧洲企业面对高电价、停产或减产压力时,中国制造商更容易维持产能利用率、报价稳定性和供应链连续性;欧洲资料显示,能源危机期间批发电价一度大幅飙升,且危机后企业能源价格仍显著高于2021年前水平 (#source-1)(#source-5)。 但这种韧性不是免费的。煤电依赖提高了碳排放强度,也使出口企业面" source context "中国煤电底座如何让制造业在全球能源危机中更抗压 | 回答 | Studio Global" Reference image 2: visual subject "中国能“沉得住气”,不是被动等待,而是主动构建的多层防御体系:短期靠储备托底,中期靠多元进口稳供应,长期靠新能源与电动化从根本上降低石油依赖。中国构建的“能源安全缓冲系统”,包括战略石油储备、多元化进口渠道以及本土能源技术的发展。这种全方位的能源安全战略,正是对中东危机带来的警示的直接回应。 财经号声明: 本文由入驻中金在线财经号平台的作者撰写,观点仅代表" source context "应对霍尔木兹石油运输中断有多难,中国为什么能做到?_中金在线财经号
openai.com
China’s coal-heavy power system worked like a practical shock absorber during the 2021–2023 global energy shock. It did not eliminate energy risk. It did, however, reduce the direct exposure of Chinese factories to international natural-gas prices and to the kind of electricity-price surge that hit Europe hardest.
In 2023, coal generated 5,350 TWh of electricity in China, or 58.2% of total generation. The International Energy Agency (IEA) also notes that more than half of the world’s coal-fired generation takes place in China. That scale matters: behind China’s manufacturing base sat a huge, mostly domestic, dispatchable power system at the same time global gas, coal and power prices were moving sharply higher.
Studio Global AI
Continue your research
This page includes a source-backed answer you can continue inside Studio Global.
What is the short answer to "China’s coal cushion: why its factories weathered the energy shock better"?
China’s coal heavy power system did not eliminate energy risk, but it gave manufacturers a short to medium term buffer: in 2023, coal generated 5,350 TWh of electricity, or 58.2% of China’s total.[34]
What are the key points to validate first?
China’s coal heavy power system did not eliminate energy risk, but it gave manufacturers a short to medium term buffer: in 2023, coal generated 5,350 TWh of electricity, or 58.2% of China’s total.[34] Compared with Europe, China’s advantage was mainly lower direct exposure to gas driven electricity price spikes; EU reporting says industrial gas and electricity prices remained 2–4 times higher than in the EU’s main...
What should I do next in practice?
Compared with Japan and South Korea, the point is not that Chinese power was always cheaper, but that China had a domestic coal to power security cushion those economies could not easily replicate.[3][14][32]
The first layer of resilience was fuel. China is still a net importer of fossil fuels, and it imported about 7% of its coal supply in 2022. But it is also the world’s largest coal producer, producing nearly five times as much as India, the second-largest producer.
That domestic base separates China from economies whose power costs are more tightly linked to imported natural gas. The IEA’s Electricity Market Report 2023 describes how the post-pandemic recovery ran into record energy prices, with soaring natural-gas and coal prices sharply raising power-generation costs and adding to inflation. In that setting, a power system anchored in domestic coal could blunt part of the direct pass-through from international gas prices to industrial electricity costs.
This is not the same as saying coal power was always cheap. It means the main shock channel was different. For many Chinese factories, the vulnerability was less about European-style gas-linked electricity prices and more about whether coal supply, grid dispatch and local power management could keep production running.
Dispatchable power mattered as much as price
Coal’s second advantage was dispatchability: plants can be called on when hydropower is weak, demand peaks or the grid is under stress. In 2023, droughts in India and China reduced hydropower output, and coal-fired generation rose, more than offsetting coal-power declines in the United States and the European Union, according to the IEA.
For manufacturers, energy resilience is not just a line item on a utility bill. It is the ability to keep shifts running, meet delivery windows and avoid interruptions in production. China’s industrial sector accounts for about two-thirds of the country’s total energy consumption; in 2019, manufacturing alone accounted for about 55% of national energy use, and 59.6% of manufacturing energy came from coal.
That is why the coal-power base mattered to the factory floor. It gave China a large source of controllable electricity at moments when weather, fuel markets and demand spikes were all testing power systems.
Europe shows the contrast
Europe’s pain point during the crisis was the much more direct transmission of gas prices into power prices and industrial costs. An EU report on energy prices and costs says the 2021–2022 energy crisis widely disrupted global and European energy markets, and that higher gas prices drove up EU wholesale electricity prices.
Prices later eased, but not back to the old normal. In 2023, the European Power Benchmark averaged €95/MWh, 57% below the record highs of 2022. Yet another EU report says the fall in wholesale prices had not fully reached retail customers, leaving household and business energy prices above pre-2021 levels; industrial gas and electricity prices, though below the crisis peak, were still 2–4 times higher than in the EU’s main trading partners.
That helps explain the nature of China’s relative advantage. It was less a blanket guarantee that every Chinese industrial product was cheaper, and more a reduction in extreme energy-cost volatility and supply uncertainty. The Jacques Delors Centre similarly notes that the gap in electricity costs for large industrial companies between EU countries and the United States and China widened significantly in 2023, even after European price-support mechanisms were taken into account.
Japan and South Korea: a more careful comparison
The comparison with Japan and South Korea needs more caution. The available evidence does not prove that China’s industrial electricity prices were lower in every period or for every sector. What is clearer is that China has a domestic coal base that Japan and South Korea cannot easily replicate.
Japan was exposed to the fuel-import shock. In 2022, Japan’s CIF (cost, insurance and freight) coal spot price averaged $225 per tonne, up 45% from 2021. South Korea, meanwhile, has been managing the policy trade-off between coal transition and reliable, affordable power. An OECD report says South Korean coal-fired generation fell from 240 TWh in 2018 to 200 TWh in 2021, with coal’s share of the power mix dropping from 42% to 34%.
So China’s resilience relative to Japan and South Korea is best understood as a thicker fuel-security margin, not as proof of universally lower power prices. When imported fuel markets are volatile, a large domestic coal-to-power system can slow and soften part of the shock that reaches manufacturers.
The cushion came with real costs
The coal buffer was never free.
First, China itself was not immune to coal-supply stress. In 2021, coal production failed to keep pace with demand; supply-chain problems and adverse weather contributed to power outages and idled factories. Global coal prices also surged during the crisis: in 2022, European coal prices averaged $294 per tonne and Japan’s CIF coal price averaged $225 per tonne, up 145% and 45% respectively from 2021.
Second, coal’s carbon burden is a long-term competitiveness risk. The IEA says global coal demand still grew in 2023, with the largest increase in China, and that rising coal use, mainly for power, has accounted for nearly all of the increase in global CO₂ emissions since 2019. Climate Action Tracker also identifies China’s dependence on fossil fuels, especially coal, as a major factor in global emissions.
Third, coal solves a short- to medium-term stability problem. It does not settle the future of industrial competitiveness. China’s low-carbon power is growing quickly: Ember data show that 38% of China’s electricity came from low-carbon sources in 2024, wind and solar together supplied 18%, and China contributed more than half of the global increase in both wind and solar generation.
The bottom line
China’s coal-heavy power system helped its manufacturing sector absorb part of the 2021–2023 energy shock. It worked as both a cost buffer and a form of supply insurance: large domestic coal production and dispatchable coal plants reduced direct exposure to international gas-price spikes and Europe-style electricity volatility.
Compared with Europe, the advantage was mainly less exposure to high gas prices feeding into electricity costs. Compared with Japan and South Korea, it was mainly a deeper domestic fuel-security cushion. But the same system carries risks: coal-price swings, power-management failures and high emissions all weaken the advantage. Coal helped Chinese manufacturing weather one crisis. The next test is whether low-carbon power, stronger grids and storage can reproduce coal’s reliability without locking in its carbon costs.