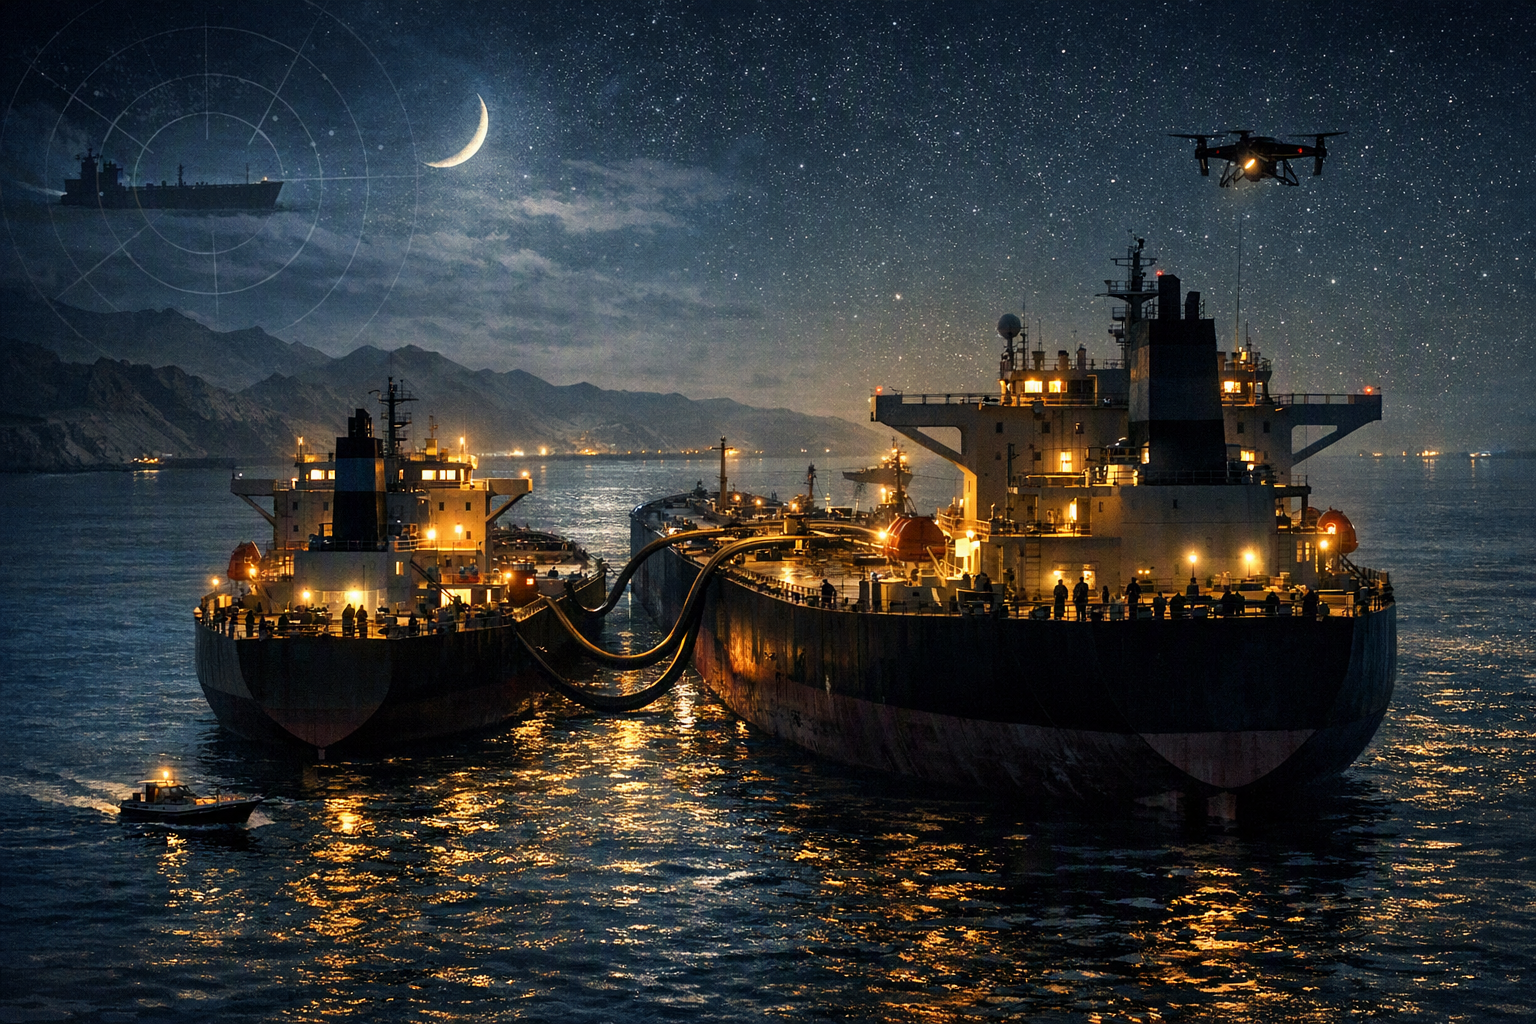
The system grew from scores of transfers involving at least 92 vessels by mid-June into a broader shuttle network. A widely cited—but lower-confidence—industry estimate puts the current dark-network flow above 4 million barrels per day, involving Iraq, the UAE, Kuwait and Qatar.
The more defensible conclusion is that the volume is substantial but opaque: U.S. officials claimed nearly 9 million bpd was leaving the region, while vessel-tracking firms estimated no more than roughly half that amount. AIS shutdowns and mid-sea transfers make both cargo origin and throughput difficult to verify.
Iraq has been the principal marginal contributor: its increased exports offset part of a UAE decline in July, when Gulf crude and condensate exports totalled 10.7 million bpd—still about 40% below pre-war levels.
Iraqi crude has also been marketed outside the strait: TotalEnergies’ trading arm Totsa offered Iraqi cargoes for loading beyond Hormuz, an indication that traders are formalizing the offshore handoff rather than relying solely on direct voyages.
Saudi Aramco and ADNOC have offered some Asian refiners crude delivered outside Hormuz through private arrangements. That lets buyers use tankers that never enter the threatened waterway, while smaller shuttles bear the transit risk.
Chinese state-owned COSCO Shipping Energy Transportation and China Merchants Energy Shipping have reportedly stopped sending their own tankers through Hormuz and the Red Sea, instead collecting crude outside the Gulf. China therefore remains a major buyer but is shifting the most dangerous leg to Gulf-side shuttles and non-Chinese shipping.
The covert flow prevented a complete physical cutoff, while Iraq’s higher shipments, Saudi and UAE alternative-delivery offers, and China’s adjustment of import demand reduced the immediate shortage. Bloomberg reported that these clandestine flows helped keep Brent broadly around $80–$90 rather than the $150 level feared at the start of the war.
Demand adjustment mattered as much as supply. China’s July crude arrivals were 8.41 million bpd, and Reuters characterized China as doing much of the demand-side adjustment needed to absorb reduced Middle East shipments.
This is a price cap, not a restoration of normal supply. Regional exports remained about 40% below pre-war levels in July, and the IEA projected a global deficit of 1.8 million bpd for the quarter amid the escalation.
Military risk: Iranian attacks have already slowed ship-to-ship activity in the Gulf of Oman; UAE authorities said Iran attacked two ADNOC vessels in Hormuz. A renewed campaign against shuttle tankers, transfer areas, pilots or escort assets could quickly halt the system.
Safety and environmental risk: Night transfers, close-quarters maneuvering, AIS blackouts and rushed cargo handoffs raise collision, grounding and spill risks, while obscured tracking delays rescue and pollution response. I could not verify a reliable current aggregate count of casualties or spill volumes from the sources retrieved.
Tanker and insurance constraint: The workaround is tanker-intensive because one export cargo can require a Gulf shuttle plus an ocean-going tanker. Reuters has already reported tanker shortages affecting other regional loadings, suggesting the network competes for scarce vessels and pushes up freight, insurance and war-risk costs.
Alternative routes are not secure substitutes: Saudi Red Sea exports can face Houthi attacks—one was claimed against a Saudi tanker off Yanbu—and an Oman-facing or Fujairah delivery point does not eliminate exposure to regional escalation.
Bypass-pipeline limits: Saudi and UAE pipelines that bypass Hormuz have finite capacity and are fixed, visible assets; the retrieved reporting does not establish that they can compensate for the lost normal seaborne flows. Their disruption would make the offshore network even more important.
LNG contagion: The evidence retrieved does not substantiate a specific, current force-majeure declaration for LNG cargoes. But interruptions to Qatari LNG or shipping capacity would compound the oil shock, competing for vessels and increasing Asian energy-security pressure.
China is the critical demand buffer—but its usable inventories are uncertain: China can moderate purchases or draw inventories, but neither the level nor commercial availability of its stockpiles is transparent. If refiners resume buying aggressively, inventories prove lower than assumed, or Beijing requires secure direct deliveries rather than offshore handoffs, the apparent supply buffer could disappear quickly. China’s own state shipping companies’ avoidance of Hormuz underscores that risk.
The central point is that the dark network has reduced the probability of an immediate $150 oil spike, but it has transferred risk into a concentrated, difficult-to-insure system of small vessels, offshore transfers and opaque inventories. A few successful attacks, a major spill, or loss of escort/tanker availability could turn a managed shortage into a sharp physical and price disruption.