Saudi Aramco’s September Oil Strategy: Why Asian Refiners Want Alternatives to Yanbu
Saudi Arabia is preserving September 2026 crude exports by negotiating loading points case by case, but the $2 per barrel Arab Light discount for Asia may not cover the extra freight, longer transit times and security... Asian buyers are resisting Yanbu because tankers face heightened danger around the Red Sea and B...
Published byEdited with GPT-5.6 LunaImages generated with GPT Image 1.5
Saudi Arabia is preserving September 2026 crude exports by negotiating loading points case by case, but the $2 per barrel Arab Light discount for Asia may not cover the extra freight, longer transit times and security...
Asian buyers are resisting Yanbu because tankers face heightened danger around the Red Sea and Bab el Mandeb; Sidi Kerir via Egypt’s SUMED pipeline offers a safer alternative, but can add 20–25 days to the voyage and...
The disruption has not necessarily reduced Aramco’s stated export capacity, but it has made shipments less transparent and more expensive to deliver, shifting much of the operational risk from the producer to refiners.
How have escalating Houthi attacks and the resulting shipping, insurance, and route risks reshaped Saudi Arabia’s crude-export strategy forSaudi Arabia is using alternative export routes as Red Sea security risks complicate September crude deliveries to Asia.
AI Prompt
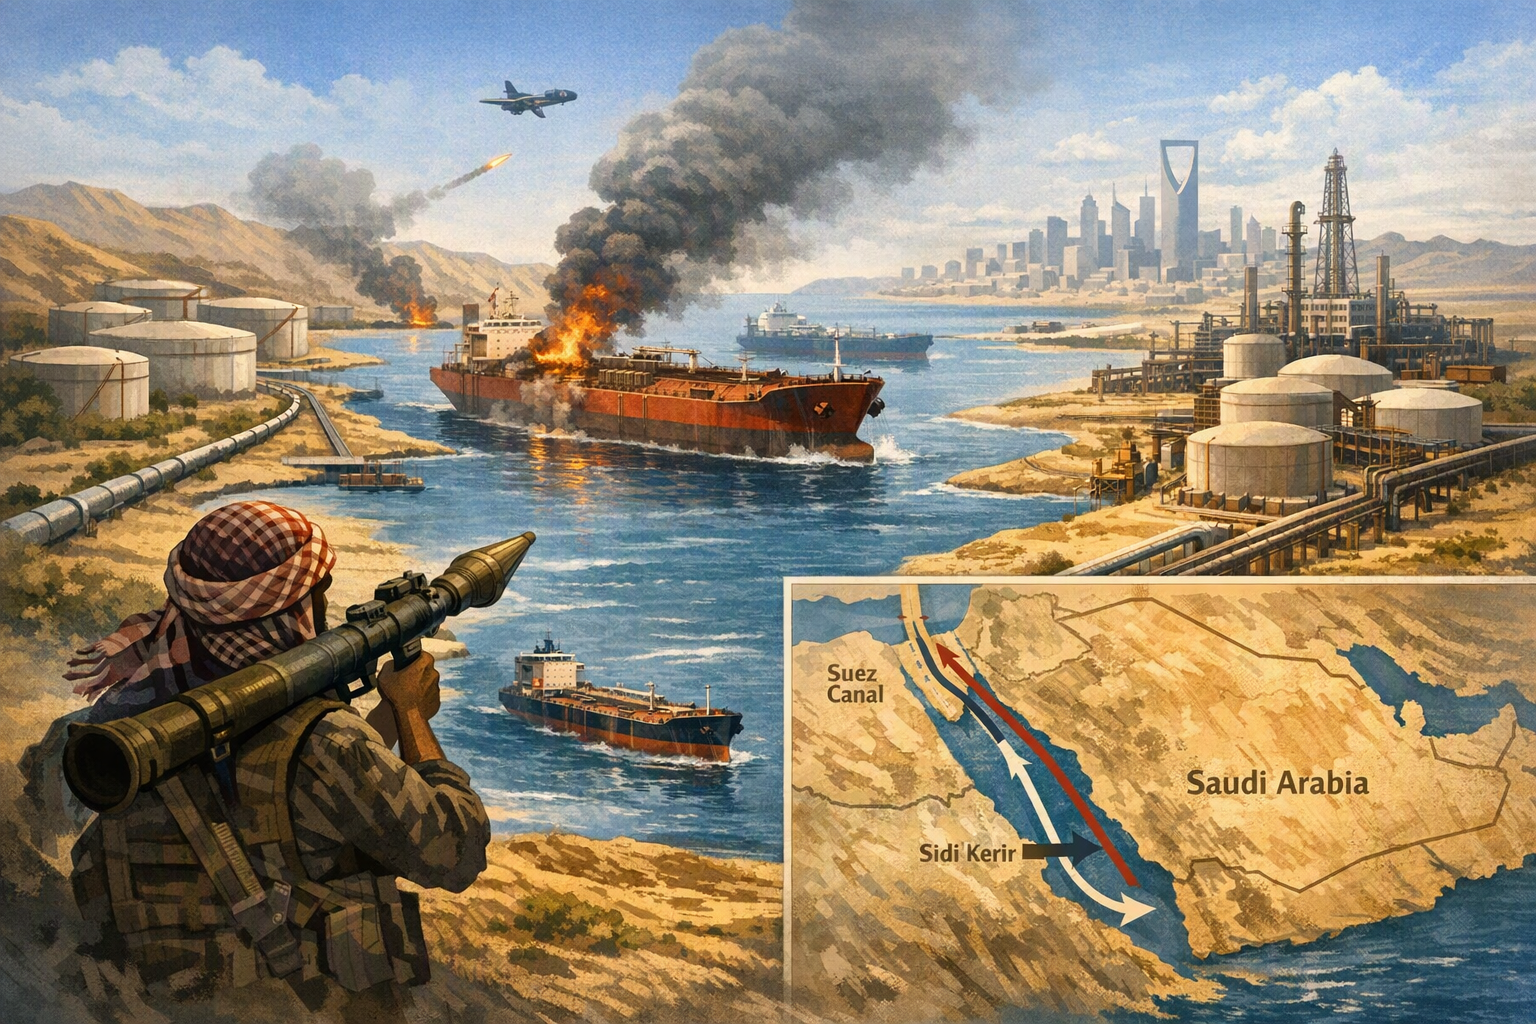
Create a landscape editorial hero image for this Studio Global article: How have escalating Houthi attacks and the resulting shipping, insurance, and route risks reshaped Saudi Arabia’s crude-export strategy for. Article summary: Saudi Arabia’s September strategy has shifted from a simple Yanbu-to-Asia Red Sea route to a flexible, negotiated export system: reroute barrels through Egypt’s SUMED pipeline and Sidi Kerir when possible, allocate cargo. Topic tags: general, news, general web, user generated. Style: premium digital editorial illustration, source-backed research mood, clean composition, high detail, modern web publication hero. Use reference image context only for broad subject, composition, and topical grounding; do not copy the exact image. Avoid: logos, brand marks, copyrighted characters, real person likenesses, fake screenshots, UI text, readable text, watermarks, charts wi
openai.com
Saudi Aramco’s September 2026 export strategy is no longer a straightforward port-to-customer program. Instead, the company is using a flexible mix of Yanbu loadings, Egypt’s SUMED pipeline and Sidi Kerir deliveries, along with private negotiations for crude outside major regional chokepoints. The approach keeps barrels moving, but it also makes the final cost, timing and risk of each cargo more important than the official selling price alone.
Why Yanbu has become difficult for Asian buyers
Yanbu gives Saudi Arabia a way to move crude from its eastern oil fields to the Red Sea through the East-West Pipeline. But cargoes heading from Yanbu to Asia generally remain exposed to the Red Sea and the Bab el-Mandeb route, where Houthi attacks and threats have made shipowners more cautious.
Studio Global AI
Continue your research
This page includes a source-backed answer you can continue inside Studio Global.
What is the short answer to "Saudi Aramco’s September Oil Strategy: Why Asian Refiners Want Alternatives to Yanbu"?
Saudi Arabia is preserving September 2026 crude exports by negotiating loading points case by case, but the $2 per barrel Arab Light discount for Asia may not cover the extra freight, longer transit times and security...
What are the key points to validate first?
Saudi Arabia is preserving September 2026 crude exports by negotiating loading points case by case, but the $2 per barrel Arab Light discount for Asia may not cover the extra freight, longer transit times and security... Asian buyers are resisting Yanbu because tankers face heightened danger around the Red Sea and Bab el Mandeb; Sidi Kerir via Egypt’s SUMED pipeline offers a safer alternative, but can add 20–25 days to the voyage and...
What should I do next in practice?
The disruption has not necessarily reduced Aramco’s stated export capacity, but it has made shipments less transparent and more expensive to deliver, shifting much of the operational risk from the producer to refiners.
The shipping risk is visible in tanker behavior. Analysts said recent Yanbu loadings were conducted “dark,” with vessels switching off tracking signals to reduce their visibility. Estimates of Yanbu loadings also varied sharply between data providers, underscoring how difficult it has become to monitor the trade reliably.
For refiners, the problem is not only whether a cargo can be loaded. They must also secure a willing vessel, manage security and freight costs, plan for possible delays and account for uncertainty over the arrival date. Those risks can outweigh the appeal of a discounted crude cargo.
The $2 discount does not equal the delivered price
Aramco set its September Arab Light official selling price for Asia at $2 per barrel below the Oman/Dubai benchmark. That was reported as the lowest level since 2020 and was intended to support demand in a disrupted market.
However, the official price is only one part of a refiner’s calculation. Cargoes loaded from an alternative port can carry different freight, handling and scheduling costs. A buyer must therefore compare the all-in delivered cost—not simply the benchmark discount—with the cost of sourcing another crude grade or declining a monthly lifting.
This explains why refiners have pressed for additional discounts on cargoes delivered through alternative routes. Aramco was also considering a separate official price for crude shipped from Sidi Kerir, reflecting the fact that a Mediterranean loading point does not have the same logistics as a conventional Persian Gulf delivery.
Sidi Kerir offers safety at the cost of time
Saudi Arabia can move crude across Egypt through the SUMED system and load it at Sidi Kerir on the Mediterranean. This avoids sending the cargo through the most exposed part of the Red Sea. Saudi exports through the Suez route rose 106% week on week to 1.06 million barrels per day after the maritime embargo announcement, while exports through Bab el-Mandeb fell to zero in the period reported by Kpler.
The alternative is not frictionless. An Asia-bound tanker leaving the Mediterranean may need to sail around Africa rather than use Bab el-Mandeb. Aramco’s chief executive said the Mediterranean route can add 20–25 days compared with the Bab el-Mandeb route. That means higher freight and financing costs, more inventory tied up at sea and less certainty for refinery scheduling.
Data from Kpler cited by CNBC showed Sidi Kerir exports more than doubled in August to about 2.3 million barrels per day from roughly 1 million barrels per day in July, with most of the increase attributed to Saudi crude.
Why buyers are receiving different instructions
The September arrangements are not uniform across Asia. Aramco reportedly asked Japanese and South Korean refiners to collect some cargoes at Sidi Kerir, while most processors in China, Taiwan and India were asked to collect at Yanbu.
That split appears to reflect buyer-specific negotiations rather than a single regional policy. Each refiner has different access to tankers, port arrangements, contract terms, risk tolerance and ability to absorb a longer voyage. Aramco has also negotiated other workarounds, including offers of some Arab Medium and Arab Heavy cargoes through ship-to-ship transfers off Fujairah in the UAE.
Term contracts do not necessarily guarantee that every monthly allocation will be lifted under every condition. Reporting indicated that at least one refiner could forgo its September allocation if the cost of moving crude from Sidi Kerir around Africa became too high.
What the disruption means for Aramco and the oil market
The rerouting shows that Saudi export capacity and normal export operations are different things. Aramco has said Houthi attempts to disrupt Red Sea shipping have not reduced its export capacity. The company has also increased flows through the East-West Pipeline toward Yanbu, which has a stated capacity of 7 million barrels per day.
But maintaining capacity now requires longer routes, ad hoc allocations and less visible tanker movements. The result is a supply chain that may still deliver the crude, but with more uncertainty and a larger share of the logistical burden placed on buyers.
Aramco’s earnings illustrate the difference between producer economics and refiner economics. The company reported second-quarter adjusted net income of $33.4 billion, up 33% from a year earlier, as higher crude prices more than offset the effect of lower sales volumes and shipping disruption.
For Asian refiners, higher oil prices do not provide the same protection. They face the cost of securing feedstock, transporting it over longer distances and keeping plants supplied on schedule. The central issue for September is therefore not whether Saudi crude is cheap at the loading point. It is whether the barrel remains competitive after route risk, freight, delay and insurance considerations are included.