The Hormuz Crisis Is Now a Delivered-Cost Shock, Not Just an Oil Shock
The effective closure of the Strait of Hormuz has shifted the crisis from headline oil prices to the delivered cost of energy and goods. Hormuz traffic has fallen from more than 100 ships a day before the conflict to only a handful on some days, reducing effective tanker capacity and raising the cost and risk of eve...
Published byEdited with GPT-5.6 LunaImages generated with GPT Image 1.5
The effective closure of the Strait of Hormuz has shifted the crisis from headline oil prices to the delivered cost of energy and goods.
Hormuz traffic has fallen from more than 100 ships a day before the conflict to only a handful on some days, reducing effective tanker capacity and raising the cost and risk of every alternative route.
Strategic reserves and distant suppliers can prevent immediate shortages, but they cannot recreate the short, low risk Gulf to Asia trade route.
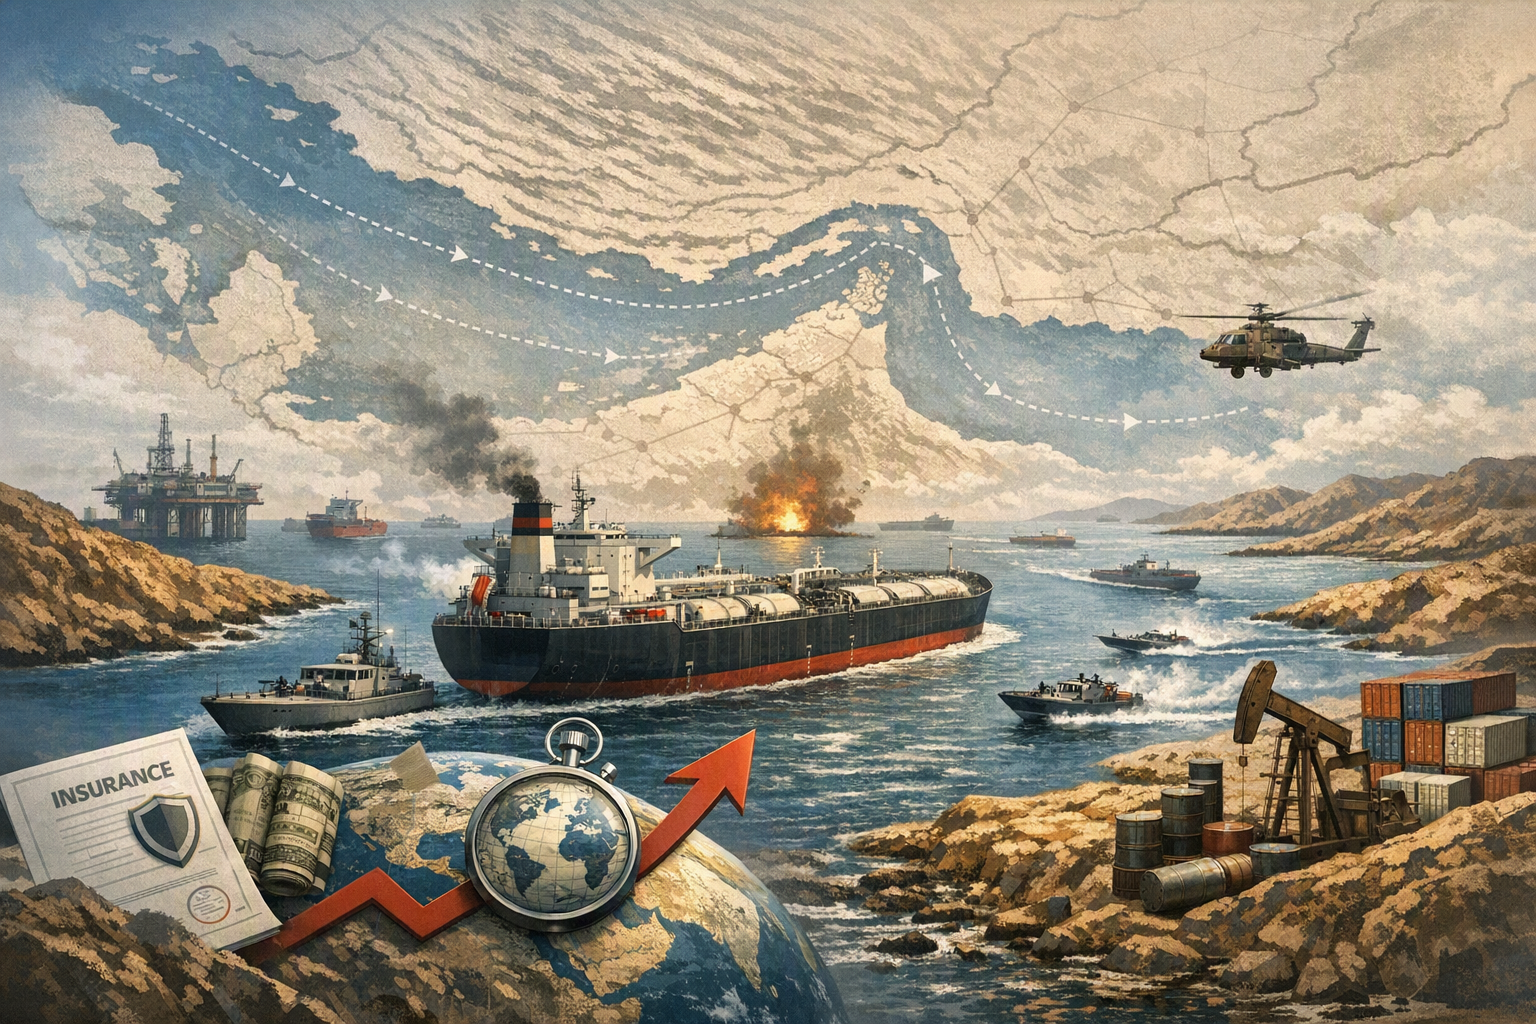
How has the effective closure of the Strait of Hormuz for nearly six months transformed the conflict from an oil-price crisis into a broaderAn editorial visualization of the Strait of Hormuz disruption and its effects on global shipping.
AI Prompt
Create a landscape editorial hero image for this Studio Global article: How has the effective closure of the Strait of Hormuz for nearly six months transformed the conflict from an oil-price crisis into a broader. Article summary: The crisis has become a delivered-cost shock rather than simply an oil-price shock. Even with Brent near $89 per barrel, the effective loss of Hormuz adds exceptionally high tanker freight, war-risk insurance, longer voy. Topic tags: general, news, general web, government, education. Style: premium digital editorial illustration, source-backed research mood, clean composition, high detail, modern web publication hero. Use reference image context only for broad subject, composition, and topical grounding; do not copy the exact image. Avoid: logos, brand marks, copyrighted characters, real person likenesses, fake screenshots, UI text, readable text, watermarks, c
openai.com
The Strait of Hormuz crisis is no longer best understood as a simple oil-price spike. It has become a delivered-cost shock: the price paid for energy and imported goods after tanker freight, war-risk insurance, longer voyages, substitute crude and tighter shipping capacity are added to the benchmark crude price.
That distinction explains why an economy can still obtain fuel while facing higher transport costs, weaker trade balances and broader inflation pressure.
From an oil disruption to a shipping constraint
Hormuz normally serves as a critical route for Gulf oil, gas and other commodity exports. After the conflict and attacks on commercial vessels, traffic through the strait fell from more than 100 ships daily before the war to a trickle in the early phase of the disruption. By July 17, just three commodity vessels crossed in a day, according to shipping data cited by Reuters. In August, the five-day average was around 13 vessels, near a three-month low.
The economic effect is larger than the number of barrels that fail to move. When vessels avoid the waterway, remain outside the Gulf or refuse to enter without exceptional protection, the market loses effective tanker capacity. Available ships must travel farther, spend more time on each voyage and absorb higher security and insurance costs. A vessel can therefore be technically available while still being uneconomic or unwilling to serve the route.
Shipping rates show how quickly that risk becomes a commodity cost. Middle East–China very large crude carrier rates exceeded $400,000 per day early in the conflict. The extra expense is layered on top of the crude benchmark, rather than fully captured by it.
Why Brent alone understates the shock
Brent is a useful reference price, but it is not the final price paid by a refinery or importer. The delivered bill can also include:
tanker freight and fuel;
war-risk insurance and security charges;
longer voyages and lower vessel utilization;
premiums for replacement grades and distant suppliers; and
financing, storage and logistics costs created by uncertainty.
That is why a relatively moderate move in the headline benchmark can coexist with a much sharper increase in the cost of getting crude to Asia. The route disruption changes the geography and reliability of supply, not only the global price signal.
Asian refiners have responded by looking beyond the Gulf. Japan’s government reported progress in securing crude from the United States, including Alaska, as well as Latin America, the Asia-Pacific region, Central Asia, Africa and Canada. Other Asian refiners also bought U.S. crude for later delivery while Hormuz remained effectively closed.
Studio Global AI
Continue your research
This page includes a source-backed answer you can continue inside Studio Global.
What is the short answer to "The Hormuz Crisis Is Now a Delivered-Cost Shock, Not Just an Oil Shock"?
The effective closure of the Strait of Hormuz has shifted the crisis from headline oil prices to the delivered cost of energy and goods.
What are the key points to validate first?
The effective closure of the Strait of Hormuz has shifted the crisis from headline oil prices to the delivered cost of energy and goods. Hormuz traffic has fallen from more than 100 ships a day before the conflict to only a handful on some days, reducing effective tanker capacity and raising the cost and risk of every alternative route.
What should I do next in practice?
Strategic reserves and distant suppliers can prevent immediate shortages, but they cannot recreate the short, low risk Gulf to Asia trade route.
These measures preserve physical availability, but the replacement barrel is not equivalent to the old barrel economically. A longer route and a more complicated procurement network can keep refineries operating while permanently increasing the security-and-distance premium embedded in the supply chain.
The shock is spreading beyond oil tankers
The same maritime risks affect container shipping. Reuters reported that container rates from Asia to the United States had doubled after the conflict began, while bunker fuel prices rose 55%. Xeneta data cited in June showed spot-rate increases of 192% on Asia–U.S. trades and 106% into North Europe, with about 10% of the global container fleet affected by the disruption.
Those increases matter because containerized trade includes far more than energy. Higher ocean freight and fuel costs can feed into the landed price of electronics, clothing, machinery, food inputs and industrial components. Importers may absorb some of the increase, renegotiate contracts or bring goods forward, but sustained disruption eventually puts pressure on margins and consumer prices.
The result is a broader transport-cost and inflation channel:
conflict reduces safe passage through the chokepoint;
vessels reroute, wait or require higher compensation;
freight, insurance and fuel costs rise;
importers pay more for energy and manufactured goods; and
higher input costs move through logistics, production and retail.
This does not mean every country experiences the same inflation rate or the same physical shortage. It means the cost structure of global trade becomes more expensive and less predictable.
Japan is the clearest case study
Japan shows how the shock moves from maritime security into national economic data. The country relies heavily on imported energy, and about 93% of its oil imports normally move through Hormuz, according to the Center for Strategic and International Studies.
Japan’s June imports rose 25.4% year over year to a record ¥11.3 trillion. Exports increased 19.3% to ¥10.9 trillion, but imports grew faster, leaving a ¥406.9 billion trade deficit.
The composition of the bill is especially revealing. Japan imported 13.7% less crude by volume year over year, yet the value of those purchases rose 59.3% as the yen-denominated unit cost reached a record. Separately, the customs-cleared crude import price reached ¥117,684 per kilolitre in June, the highest since comparable records began in 1979.
That is the signature of a delivered-cost crisis: fewer barrels can still generate a much larger import bill when price, currency and logistics all move against the buyer.
The burden is not limited to the energy sector. A survey cited by Oilprice.com reported that about 90% of Japanese companies said rising energy prices were having a negative impact. Higher crude and refined-fuel costs can affect transport operators, utilities, manufacturers, distributors and households simultaneously.
What it means for downstream fuel importers
Countries farther from the Gulf may avoid direct dependence on Hormuz crude and still feel the shock. Australia, for example, can be exposed through imported refined fuels, Asian refinery pricing, shipping charges and currency movements even when domestic stations remain supplied.
That distinction matters for policy and business planning. A country may avoid rationing but still face higher petrol, diesel, aviation-fuel and freight costs. Those costs can then reach agriculture, construction, road transport and retail. Physical availability is therefore not the same as affordability or price stability.
The impact will vary by inventory levels, refining capacity, contract structure, currency and access to alternative suppliers. The supplied evidence supports a clear transmission mechanism, but it does not establish a single inflation outcome for every downstream economy.
Reserves and rerouting buy time, not normality
Governments can reduce the immediate risk by releasing strategic stocks, redirecting cargoes and broadening supplier networks. Japan began releasing oil stocks and pursuing alternative imports after the de facto closure, using its reserves and procurement relationships to limit panic and maintain continuity.
Those measures are valuable, but temporary. Reserves decline as they are consumed. Distant suppliers require more shipping time and may compete for the same vessels. New routes can face their own infrastructure limits, while insurance and security costs remain elevated as long as the waterway is unsafe.
Even after a diplomatic agreement or partial reopening, shipping may not normalize immediately. A July assessment noted that mines, war-risk insurance and confidence would still affect the return of tanker traffic. Container-shipping data likewise suggested that a full recovery of ocean supply networks could take months, even in a best-case reopening scenario.
The broader lesson for energy security
The Hormuz crisis demonstrates that energy security is not binary. A supply chain can avoid an outright shortage and still suffer a major economic shock because the replacement supply is slower, farther away and more expensive to insure.
For markets and policymakers, the relevant measure is therefore not only the Brent quote or the number of barrels available. It is the all-in delivered cost of moving energy and goods from origin to buyer.
Reserves, supplier diversification and redesigned logistics can preserve availability. They cannot fully restore the efficiency of a short, established maritime route while the chokepoint remains effectively closed. That is how an oil-price crisis becomes a global transport-cost and inflation crisis.
japantimes.co.jpJapan's trade deficit widens as yen and Iran war inflate ...
japan.kantei.go.jpMinisterial Meeting on the Situation in the Middle East | Prime Minister in Action | Prime Minister's Office of Japan
csis.orgWhat Are the Implications of the Iran Conflict for Japan? - CSIS
reuters.comJapan imports jump to record high on oil price surge, complicating ...
apnews.comJapan's exports and imports grow as yen weakens