JPMorgan says tokenized money market funds currently represent roughly 5% of the stablecoin ecosystem and may only reach 10–15% even with favorable regulation, largely because securities laws limit how freely they can... The bank sees stablecoins as the crypto economy’s primary transactional cash, while tokenized mo...
Published byEdited with GPT-5.5Images generated with GPT Image 2
JPMorgan says tokenized money market funds currently represent roughly 5% of the stablecoin ecosystem and may only reach 10–15% even with favorable regulation, largely because securities laws limit how freely they can...
The bank sees stablecoins as the crypto economy’s primary transactional cash, while tokenized money market funds are better suited as yield‑generating reserve assets and treasury tools for institutions.
JPMorgan itself is building this category with Ethereum‑based funds such as MONY and JLTXX, designed for qualified investors and potential stablecoin reserve use.
How does JPMorgan view the future role of tokenized money market funds compared with stablecoins, including their current ~5% market share,JPMorgan expects stablecoins to remain the primary transactional money in crypto, with tokenized money market funds serving mainly as yield‑bearing reserve assets.
AI Prompt
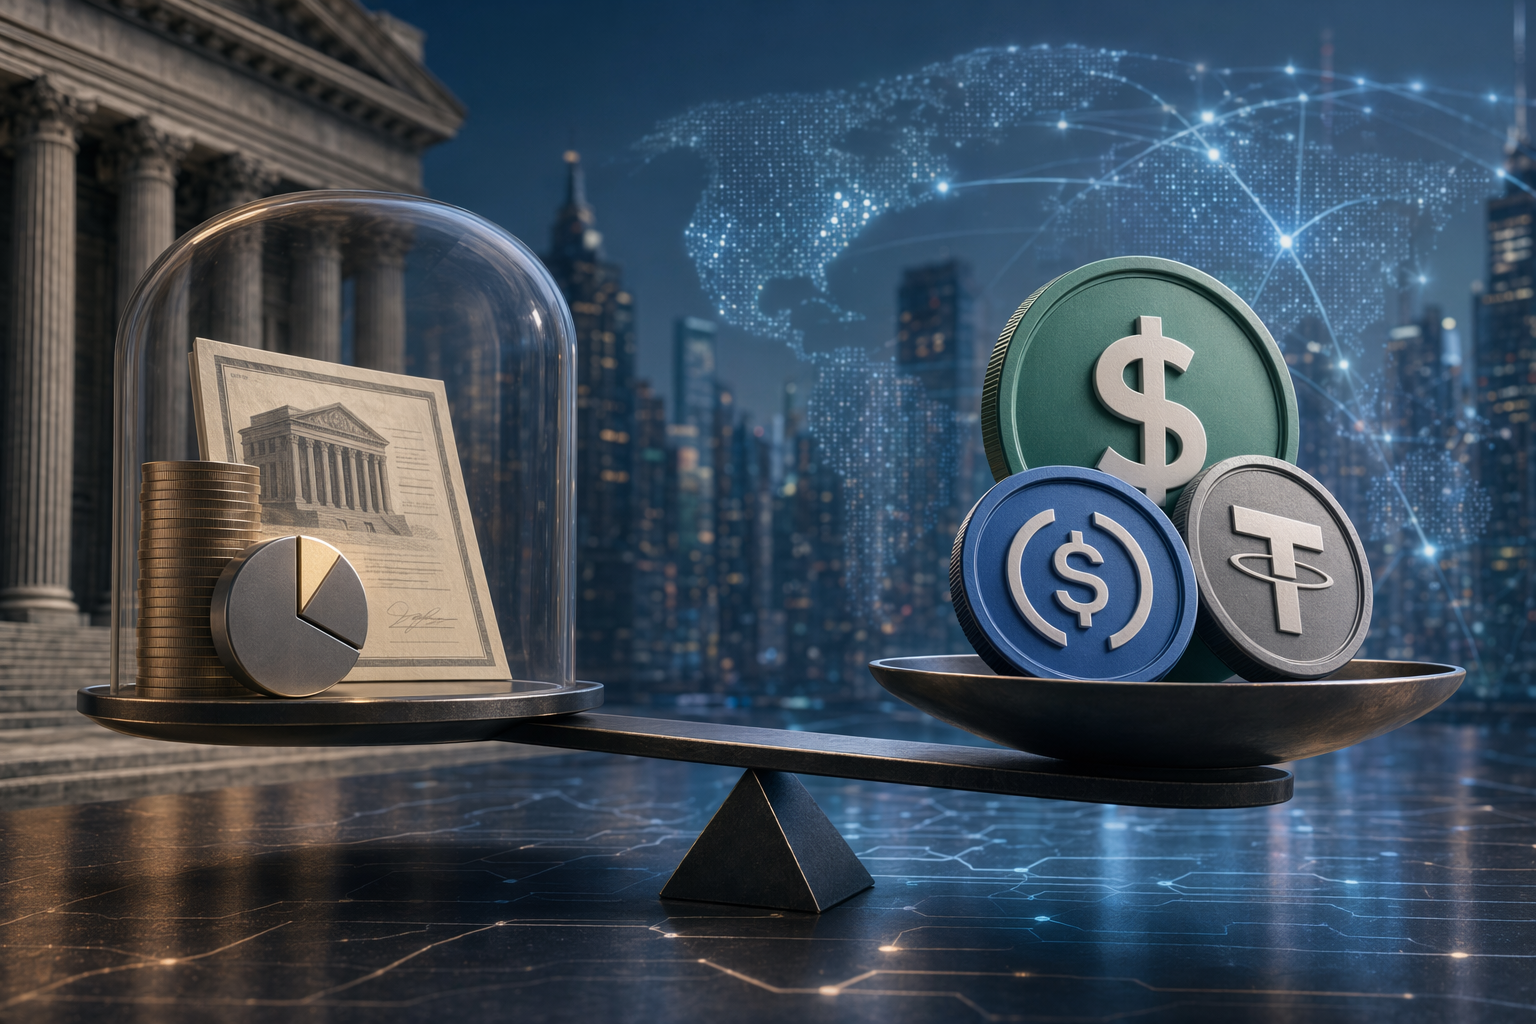
Create a landscape editorial hero image for this Studio Global article: How does JPMorgan view the future role of tokenized money market funds compared with stablecoins, including their current ~5% market share,. Article summary: JPMorgan’s view appears to be that tokenized money market funds will grow, but they are unlikely to displace stablecoins as crypto’s main transactional cash instrument. JPMorgan says tokenized MMFs are still only about 5. Topic tags: general, news, general web, user generated. Reference image context from search candidates: Reference image 1: visual subject "JPMorgan said tokenized money market funds remain a small share of the stablecoin market because of regulatory hurdles." source context "Stablecoins still dominate despite yield advantage of tokenized funds: JPMorgan" Reference image 2: visual subject "JPMorgan said tokenized money market funds remain a smal
openai.com
Tokenized money market funds (MMFs) are gaining attention as traditional finance moves on‑chain. But according to JPMorgan, they are unlikely to replace stablecoins as the dominant form of digital cash in the crypto ecosystem.
The bank’s research suggests tokenized MMFs currently represent only about 5% of the size of the stablecoin market, and even under supportive regulation they may only grow to 10–15% of that market over time. Structural regulatory constraints—particularly securities laws—limit their portability and usefulness compared with stablecoins.
Stablecoins Already Function as Crypto’s Cash Layer
JPMorgan argues that stablecoins have already become the default liquidity instrument across the digital asset ecosystem. They are widely used for trading, collateral management, settlement, cross‑border payments, and liquidity provisioning in both centralized exchanges and decentralized finance.
Studio Global AI
Continue your research
This page includes a source-backed answer you can continue inside Studio Global.
What is the short answer to "Why JPMorgan Thinks Tokenized Money Market Funds Won’t Replace Stablecoins"?
JPMorgan says tokenized money market funds currently represent roughly 5% of the stablecoin ecosystem and may only reach 10–15% even with favorable regulation, largely because securities laws limit how freely they can...
What are the key points to validate first?
JPMorgan says tokenized money market funds currently represent roughly 5% of the stablecoin ecosystem and may only reach 10–15% even with favorable regulation, largely because securities laws limit how freely they can... The bank sees stablecoins as the crypto economy’s primary transactional cash, while tokenized money market funds are better suited as yield‑generating reserve assets and treasury tools for institutions.
What should I do next in practice?
JPMorgan itself is building this category with Ethereum‑based funds such as MONY and JLTXX, designed for qualified investors and potential stablecoin reserve use.
JPMorgan says tokenized money market funds currently represent roughly 5% of the stablecoin ecosystem and may only reach 10–15% even with favorable regulation, largely because securities laws limit how freely they can... The bank sees stablecoins as the crypto economy’s primary transactional cash, while tokenized mo...
Published byEdited with GPT-5.5Images generated with GPT Image 2
JPMorgan says tokenized money market funds currently represent roughly 5% of the stablecoin ecosystem and may only reach 10–15% even with favorable regulation, largely because securities laws limit how freely they can...
The bank sees stablecoins as the crypto economy’s primary transactional cash, while tokenized money market funds are better suited as yield‑generating reserve assets and treasury tools for institutions.
JPMorgan itself is building this category with Ethereum‑based funds such as MONY and JLTXX, designed for qualified investors and potential stablecoin reserve use.
How does JPMorgan view the future role of tokenized money market funds compared with stablecoins, including their current ~5% market share,JPMorgan expects stablecoins to remain the primary transactional money in crypto, with tokenized money market funds serving mainly as yield‑bearing reserve assets.
AI Prompt
Create a landscape editorial hero image for this Studio Global article: How does JPMorgan view the future role of tokenized money market funds compared with stablecoins, including their current ~5% market share,. Article summary: JPMorgan’s view appears to be that tokenized money market funds will grow, but they are unlikely to displace stablecoins as crypto’s main transactional cash instrument. JPMorgan says tokenized MMFs are still only about 5. Topic tags: general, news, general web, user generated. Reference image context from search candidates: Reference image 1: visual subject "JPMorgan said tokenized money market funds remain a small share of the stablecoin market because of regulatory hurdles." source context "Stablecoins still dominate despite yield advantage of tokenized funds: JPMorgan" Reference image 2: visual subject "JPMorgan said tokenized money market funds remain a smal
openai.com
Tokenized money market funds (MMFs) are gaining attention as traditional finance moves on‑chain. But according to JPMorgan, they are unlikely to replace stablecoins as the dominant form of digital cash in the crypto ecosystem.
The bank’s research suggests tokenized MMFs currently represent only about 5% of the size of the stablecoin market, and even under supportive regulation they may only grow to 10–15% of that market over time. Structural regulatory constraints—particularly securities laws—limit their portability and usefulness compared with stablecoins.
Stablecoins Already Function as Crypto’s Cash Layer
JPMorgan argues that stablecoins have already become the default liquidity instrument across the digital asset ecosystem. They are widely used for trading, collateral management, settlement, cross‑border payments, and liquidity provisioning in both centralized exchanges and decentralized finance.
Studio Global AI
Continue your research
This page includes a source-backed answer you can continue inside Studio Global.
What is the short answer to "Why JPMorgan Thinks Tokenized Money Market Funds Won’t Replace Stablecoins"?
JPMorgan says tokenized money market funds currently represent roughly 5% of the stablecoin ecosystem and may only reach 10–15% even with favorable regulation, largely because securities laws limit how freely they can...
What are the key points to validate first?
JPMorgan says tokenized money market funds currently represent roughly 5% of the stablecoin ecosystem and may only reach 10–15% even with favorable regulation, largely because securities laws limit how freely they can... The bank sees stablecoins as the crypto economy’s primary transactional cash, while tokenized money market funds are better suited as yield‑generating reserve assets and treasury tools for institutions.
What should I do next in practice?
JPMorgan itself is building this category with Ethereum‑based funds such as MONY and JLTXX, designed for qualified investors and potential stablecoin reserve use.
Because they are designed to move freely between wallets, platforms, and protocols, stablecoins behave much like digital cash within crypto markets. That portability gives them a major advantage in everyday transactional use.
Why Tokenized Money Market Funds Face Structural Limits
Tokenized MMFs are fundamentally different assets. Even when represented on blockchain networks, they remain shares of regulated investment funds, which means they are treated as securities.
That classification brings multiple constraints, including:
investor eligibility and onboarding requirements
compliance with securities regulations and disclosures
transfer restrictions that limit open circulation
These rules make it harder for tokenized MMF shares to move freely across permissionless crypto infrastructure. JPMorgan describes this as a structural regulatory disadvantage compared with stablecoins.
As a result, tokenized MMFs cannot easily serve as the day‑to‑day settlement asset for decentralized markets or trading activity.
A Different Role: Yield‑Generating On‑Chain Reserves
Instead of replacing stablecoins, JPMorgan expects tokenized money market funds to fill a complementary role.
Money market funds hold short‑term government securities and similar highly liquid assets. When tokenized, they can provide institutional investors with on‑chain access to Treasury‑backed liquidity that generates yield, something most stablecoins do not provide directly.
In practice, the bank sees these funds being used for:
institutional treasury management
collateral in digital financial markets
reserve assets backing stablecoins
parking idle on‑chain cash while earning yield
This positioning aligns with how many traditional investors already use money market funds for liquidity management.
JPMorgan Is Building Tokenized Funds on Ethereum
JPMorgan is actively developing products in this category.
In December 2025, the firm launched its first tokenized money market fund, My OnChain Net Yield Fund (MONY), on the public Ethereum blockchain. The fund allows qualified investors to access yield‑bearing dollar assets on‑chain through the firm’s digital asset infrastructure.
In May 2026, the bank followed with a second Ethereum‑based product: the JPMorgan OnChain Liquidity‑Token Money Market Fund (JLTXX). This U.S. registered government money market fund invests primarily in short‑term U.S. Treasury securities and Treasury‑collateralized repurchase agreements.
JLTXX is designed partly to meet reserve requirements for stablecoin issuers and other institutions seeking regulated Treasury‑backed liquidity in digital form.
The Emerging Two‑Layer On‑Chain Money System
JPMorgan’s analysis points toward a layered financial structure in the digital asset economy:
Stablecoins: the primary transactional money used for payments, trading, and settlement.
Tokenized money market funds: yield‑bearing reserve assets and liquidity management tools for institutions.
Under this model, stablecoins continue to function as the everyday medium of exchange in crypto markets, while tokenized funds sit behind the scenes as the interest‑earning reserve layer.
Even as tokenization accelerates across financial markets, JPMorgan’s outlook suggests that the two instruments are more likely to coexist—serving different but complementary roles in the evolving on‑chain financial system.
Because they are designed to move freely between wallets, platforms, and protocols, stablecoins behave much like digital cash within crypto markets. That portability gives them a major advantage in everyday transactional use.
Why Tokenized Money Market Funds Face Structural Limits
Tokenized MMFs are fundamentally different assets. Even when represented on blockchain networks, they remain shares of regulated investment funds, which means they are treated as securities.
That classification brings multiple constraints, including:
investor eligibility and onboarding requirements
compliance with securities regulations and disclosures
transfer restrictions that limit open circulation
These rules make it harder for tokenized MMF shares to move freely across permissionless crypto infrastructure. JPMorgan describes this as a structural regulatory disadvantage compared with stablecoins.
As a result, tokenized MMFs cannot easily serve as the day‑to‑day settlement asset for decentralized markets or trading activity.
A Different Role: Yield‑Generating On‑Chain Reserves
Instead of replacing stablecoins, JPMorgan expects tokenized money market funds to fill a complementary role.
Money market funds hold short‑term government securities and similar highly liquid assets. When tokenized, they can provide institutional investors with on‑chain access to Treasury‑backed liquidity that generates yield, something most stablecoins do not provide directly.
In practice, the bank sees these funds being used for:
institutional treasury management
collateral in digital financial markets
reserve assets backing stablecoins
parking idle on‑chain cash while earning yield
This positioning aligns with how many traditional investors already use money market funds for liquidity management.
JPMorgan Is Building Tokenized Funds on Ethereum
JPMorgan is actively developing products in this category.
In December 2025, the firm launched its first tokenized money market fund, My OnChain Net Yield Fund (MONY), on the public Ethereum blockchain. The fund allows qualified investors to access yield‑bearing dollar assets on‑chain through the firm’s digital asset infrastructure.
In May 2026, the bank followed with a second Ethereum‑based product: the JPMorgan OnChain Liquidity‑Token Money Market Fund (JLTXX). This U.S. registered government money market fund invests primarily in short‑term U.S. Treasury securities and Treasury‑collateralized repurchase agreements.
JLTXX is designed partly to meet reserve requirements for stablecoin issuers and other institutions seeking regulated Treasury‑backed liquidity in digital form.
The Emerging Two‑Layer On‑Chain Money System
JPMorgan’s analysis points toward a layered financial structure in the digital asset economy:
Stablecoins: the primary transactional money used for payments, trading, and settlement.
Tokenized money market funds: yield‑bearing reserve assets and liquidity management tools for institutions.
Under this model, stablecoins continue to function as the everyday medium of exchange in crypto markets, while tokenized funds sit behind the scenes as the interest‑earning reserve layer.
Even as tokenization accelerates across financial markets, JPMorgan’s outlook suggests that the two instruments are more likely to coexist—serving different but complementary roles in the evolving on‑chain financial system.
en.bloomingbit.ioJPMorgan Says Tokenized MMFs Unlikely to Surpass Stablecoins ...
moomoo.comStablecoins Retain the Edge Over Tokenized Money Market Funds ...
am.jpmorgan.comTokenization of Money Market Funds - J.P. Morgan Asset Management