Why Google may want a direct TSMC line for TPUs — without dropping MediaTek
There is no official confirmation that Google has decided to bypass MediaTek entirely; Business Weekly reported that MediaTek declined to comment and TSMC said it does not comment on individual customer details[6]. Reports still describe MediaTek as handling I/O die design, wafer procurement, back end packaging inte...
Published byEdited with GPT-5.5Images generated with GPT Image 2
There is no official confirmation that Google has decided to bypass MediaTek entirely; Business Weekly reported that MediaTek declined to comment and TSMC said it does not comment on individual customer details[6].
Reports still describe MediaTek as handling I/O die design, wafer procurement, back end packaging integration, quality control support and TSMC ordering for Google TPU projects[2][10].
The real pressure point is CoWoS: reports link Google TPU ramp up to TSMC advanced packaging capacity and say the 2027 CoWoS allocation for MediaTek’s Google project could rise more than sevenfold[6][8].
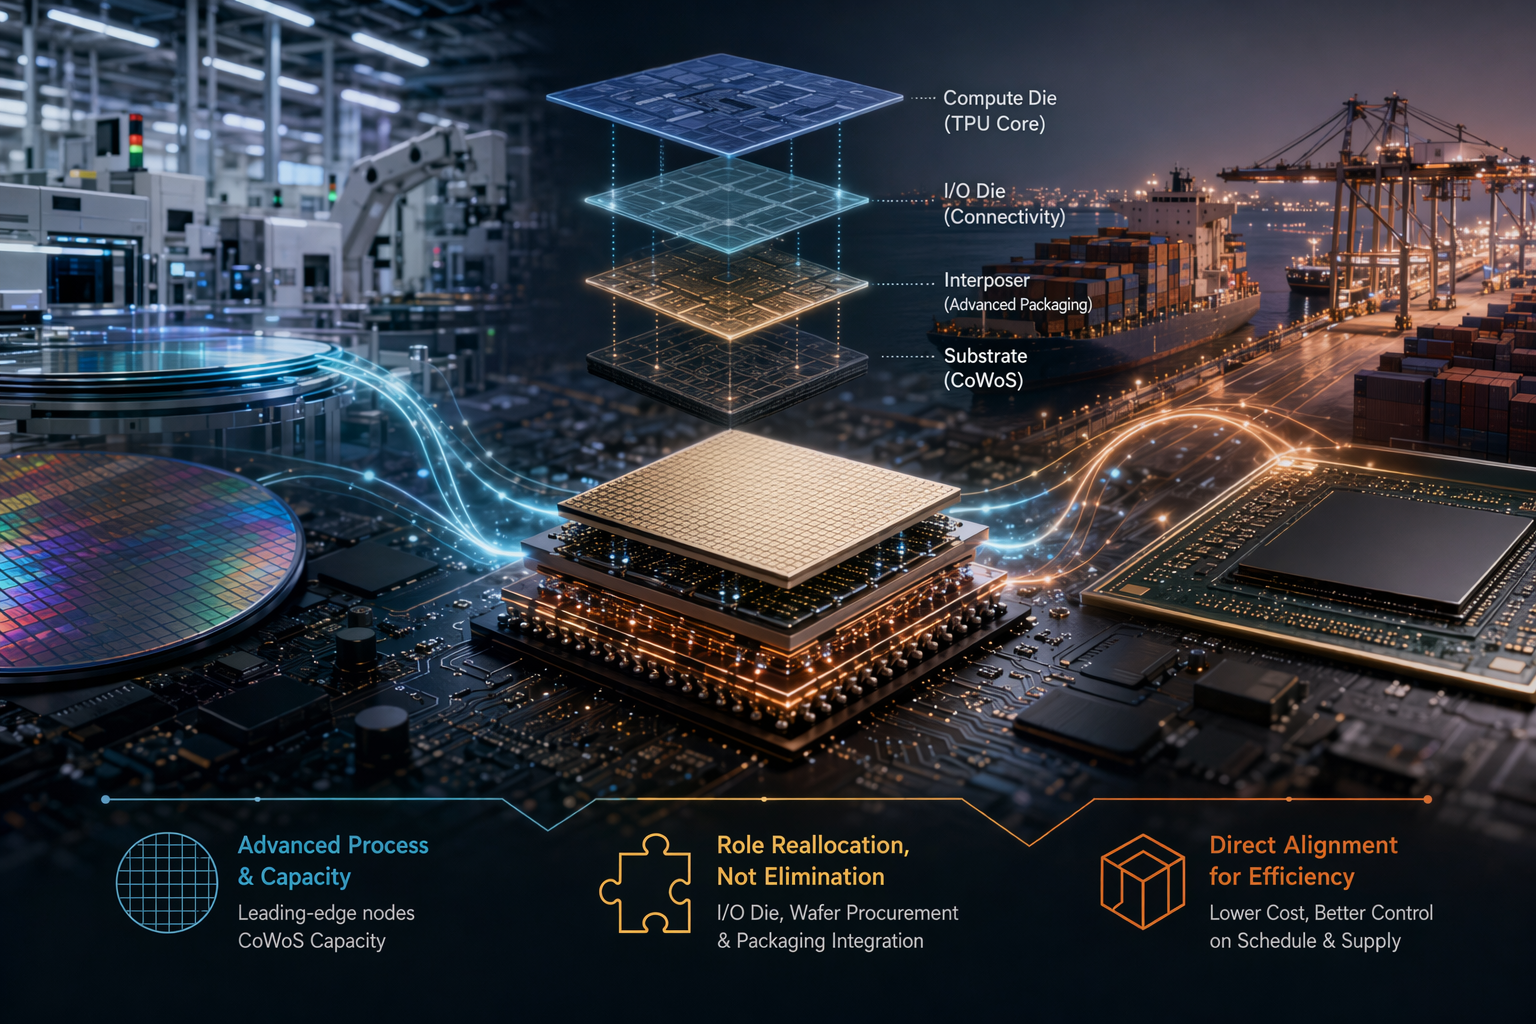
Google TPU 供應鏈變局:為何可能直連台積電,而不代表聯發科出局AI 生成示意圖:Google TPU 供應鏈討論的焦點,是先進製程與 CoWoS 封裝產能如何分配。
AI Prompt
Create a landscape editorial hero image for this Studio Global article: Google TPU 供應鏈變局:為何可能直連台積電,而不代表聯發科出局. Article summary: 目前沒有公開證據證實 Google 會完全不透過聯發科;若下單模式更直接連到台積電,核心是搶 CoWoS/先進製程產能、降低成本並掌握排程。報導仍指聯發科負責 I/O Die、晶圓採購與封裝整合,所以更像角色重分配,而非確定出局[2][6]。. Topic tags: google, tpu, tsmc, mediatek, ai chips. Reference image context from search candidates: Reference image 1: visual subject "換句話說,在CoWoS產能有限下,Google必須等待台積電擴產,才能將TPU從主要供內部使用的戰略資源,轉變為能大規模外銷、賺取巨額利潤的商品。而這段等待期,對" source context "Google的AI晶片關鍵挑戰,來自台積電? | 遠見雜誌" Reference image 2: visual subject "輝達預計自2027年起,在部分產品線引入三星作為台積電之外的第二供應商。聯發科為Google開發的3奈米TPU進展順利,預計2026年下半年量產,2027年營收貢獻上看" source context "大摩揭AI晶片供應鏈關鍵:台積電CoWoS產能無虞 聯發科TPU量產在即 — BigGo 財經" Style: premium digital editorial illustration, source-backed research mood, clean composition, high detail, modern web publication hero. Use reference image context only for broad subject, composition
openai.com
Reducing the latest Google TPU supply-chain discussion to “MediaTek has been replaced” misses the more important point. If Google builds a more direct ordering or capacity-planning relationship with TSMC, the likely goal is to control the scarce parts of production: advanced process wafers, CoWoS packaging slots, mass-production timing and cost structure.
That does not automatically mean MediaTek is out. Current reports still place MediaTek in roles such as I/O die design, wafer procurement, back-end packaging integration, communications I/O, production quality-control support and placing orders with TSMC. In other words, the question is less “Who designed the TPU?” and more “Who controls the bottleneck capacity?”
First, what has not been confirmed
There is still no public confirmation that Google has decided to bypass MediaTek completely. Business Weekly reported that MediaTek declined to comment on the relevant Google TPU reports, while TSMC said it does not comment on the business details of individual customers.
Studio Global AI
Continue your research
This page includes a source-backed answer you can continue inside Studio Global.
What is the short answer to "Why Google may want a direct TSMC line for TPUs — without dropping MediaTek"?
There is no official confirmation that Google has decided to bypass MediaTek entirely; Business Weekly reported that MediaTek declined to comment and TSMC said it does not comment on individual customer details[6].
What are the key points to validate first?
There is no official confirmation that Google has decided to bypass MediaTek entirely; Business Weekly reported that MediaTek declined to comment and TSMC said it does not comment on individual customer details[6]. Reports still describe MediaTek as handling I/O die design, wafer procurement, back end packaging integration, quality control support and TSMC ordering for Google TPU projects[2][10].
What should I do next in practice?
The real pressure point is CoWoS: reports link Google TPU ramp up to TSMC advanced packaging capacity and say the 2027 CoWoS allocation for MediaTek’s Google project could rise more than sevenfold[6][8].
So the safer reading is conditional: if Google moves some wafer or CoWoS capacity coordination closer to TSMC, that would be a shift in purchasing power, packaging control and schedule visibility. It would not, by itself, prove that MediaTek has lost every technical or engineering role in the project.
The reported split of work matters
TPU, short for Tensor Processing Unit, is Google’s custom AI accelerator and falls into the ASIC category of chips built for specific workloads. Reports describe Google as keeping the most strategic design work in-house.
TechNews reported that, in Google’s cooperation with MediaTek, Google is responsible for the Compute Die design and procurement of high-bandwidth memory, or HBM. MediaTek is reported to handle the I/O Die design, all wafer procurement and back-end packaging integration.
Inside, summarising reporting from The Information, also said the next TPU is still mostly designed by Google, while MediaTek mainly provides the communications input/output design between the TPU and related components, assists with production quality control, and serves as the party placing orders with TSMC.
That distinction is crucial. MediaTek is not described as merely a broker sitting between Google and TSMC. But it is also not described as the full architect of Google’s TPU. Its reported role sits in the I/O, manufacturing coordination, quality and packaging-integration layers. A more direct Google-TSMC link could therefore reduce MediaTek’s control over procurement and scheduling without eliminating its I/O or engineering contribution.
Why TSMC’s CoWoS capacity is the centre of gravity
For advanced AI chips, design is only half the battle. The other half is getting enough manufacturing and advanced packaging capacity to ship at scale. That is where TSMC’s CoWoS packaging becomes strategically important.
Next Apple, citing foreign media, reported that Google’s dual-supplier approach allows it to seek TSMC CoWoS advanced packaging allocation through both MediaTek and Broadcom, helping accelerate TPU v7e mass production. Business Weekly also reported that MediaTek had added TSMC advanced process and CoWoS packaging capacity for Google’s v7e and v8e projects, and that TSMC’s 2027 CoWoS capacity for MediaTek’s Google project was rumoured to increase more than sevenfold.
The timeline adds pressure. Business Weekly reported that moving from wafer production to completed CoWoS packaging and testing takes about eight to nine months. It also reported that, if later certification proceeds smoothly, output from the TPU v7e risk production run could be treated as production supply. When the bottleneck is packaging slots and production timing, it is easy to see why Google would want a clearer, more direct view of the TSMC pipeline.
Four reasons Google may want a more direct TSMC relationship
1. Securing scarce CoWoS capacity
Multiple reports connect Google’s TPU ramp with TSMC’s CoWoS capacity. If demand for TPU v7e and v8e rises quickly, direct visibility into wafer starts, packaging queues and test schedules could reduce uncertainty. For a hyperscale cloud company, the ability to know when chips will be ready can matter as much as the chip design itself.
2. Improving cost control — though direct does not automatically mean cheaper
Inside reported that Google planned to work with MediaTek on a lower-cost TPU, partly because MediaTek’s quote was lower than Broadcom’s. That suggests Google was already looking for a more cost-efficient TPU supply model.
Still, public information does not prove that direct TSMC ordering would necessarily be cheaper than the current structure. The real cost would depend on contracts, capacity commitments, packaging configuration and who carries integration risk. The better conclusion is that a closer TSMC relationship could give Google more control over cost drivers, not that it guarantees a lower bill.
3. Shortening the decision chain
In the reported MediaTek arrangement, MediaTek handles wafer procurement and back-end packaging integration. It is also described as helping with quality control and placing orders with TSMC. That means MediaTek is not only providing design-related services; it is also managing part of the manufacturing coordination chain.
If Google wants faster decisions on wafer starts, CoWoS allocation, testing and certification, a more direct role with TSMC would be a logical supply-chain adjustment. That kind of change could separate two functions that are currently linked: who supports I/O and engineering, and who controls production capacity and delivery timing.
4. Reducing dependence on any one ASIC partner
Google’s move to involve MediaTek has already been interpreted as part of a dual-supplier strategy. Next Apple reported that Google had previously relied heavily on Broadcom across TPU-related architecture, IP, I/O services and system integration, and that seeking a second source was a way to reduce exposure to cost, supply and technology-timing risks from relying too heavily on one partner.
Inside also reported that even if Google turns more toward MediaTek, its relationship with Broadcom may continue, meaning Broadcom and MediaTek could split Google TPU orders. A stronger direct relationship with TSMC would fit the same logic: Google would keep more control over the scarce manufacturing layer instead of letting any one design-service or integration partner become the single gatekeeper.
What this means for MediaTek
The current evidence points more to role redistribution than immediate exclusion. TechNews reported that MediaTek has entered the design of Google’s eighth-generation TPU, or TPUv8x, with revenue contribution expected to begin in the fourth quarter of 2026. The same report said market interpretation linked later project revenue, expected from 2028, to a possible advanced eighth-generation TPU, or TPUv8e.
TechNews also reported that one reason MediaTek won Google business from Broadcom was its SerDes IP, a high-speed communications technology used to move data efficiently between chip components. That is closely aligned with the I/O-focused role described in other reports.
So even if Google takes back more direct control over wafer purchasing, CoWoS allocation or delivery schedules, MediaTek could still remain relevant in areas such as I/O Die design, SerDes, quality control and system-level engineering support.
Three signals to watch next
First, watch CoWoS allocation. Business Weekly reported that TSMC’s 2027 CoWoS capacity for MediaTek’s Google project was rumoured to rise more than sevenfold. If that figure changes, it would directly affect the expected TPU ramp.
Second, watch the TPU v7e risk-production schedule. Business Weekly reported that MediaTek’s first Google TPU, v7e, was expected to enter risk production at the end of the first quarter of 2026. Whether that output can be treated as production supply depends on the certification process.
Third, watch whether MediaTek’s role shifts from wafer procurement and packaging integration toward I/O, SerDes, quality and engineering support. TechNews and Inside both describe MediaTek as having I/O and manufacturing-coordination responsibilities, not as having fully exited Google’s TPU programme.
Bottom line
If Google seeks a more direct path to TSMC for future TPUs, the most likely reason is control: control of CoWoS capacity, production timing, cost structure and supply-chain visibility. That is different from proving that MediaTek has been pushed out.
Based on current reporting, Google appears to be making its TPU supply chain more direct and more diversified. MediaTek’s risk is not necessarily an immediate loss of all Google TPU work. The bigger question is whether its role in wafer procurement, packaging and scheduling becomes narrower while its I/O and engineering-support role remains in place.